Where the cash hides in your stock
Most mid-sized businesses carry more stock than their service levels need. The excess is rarely in one place, and rarely visible on a single report.
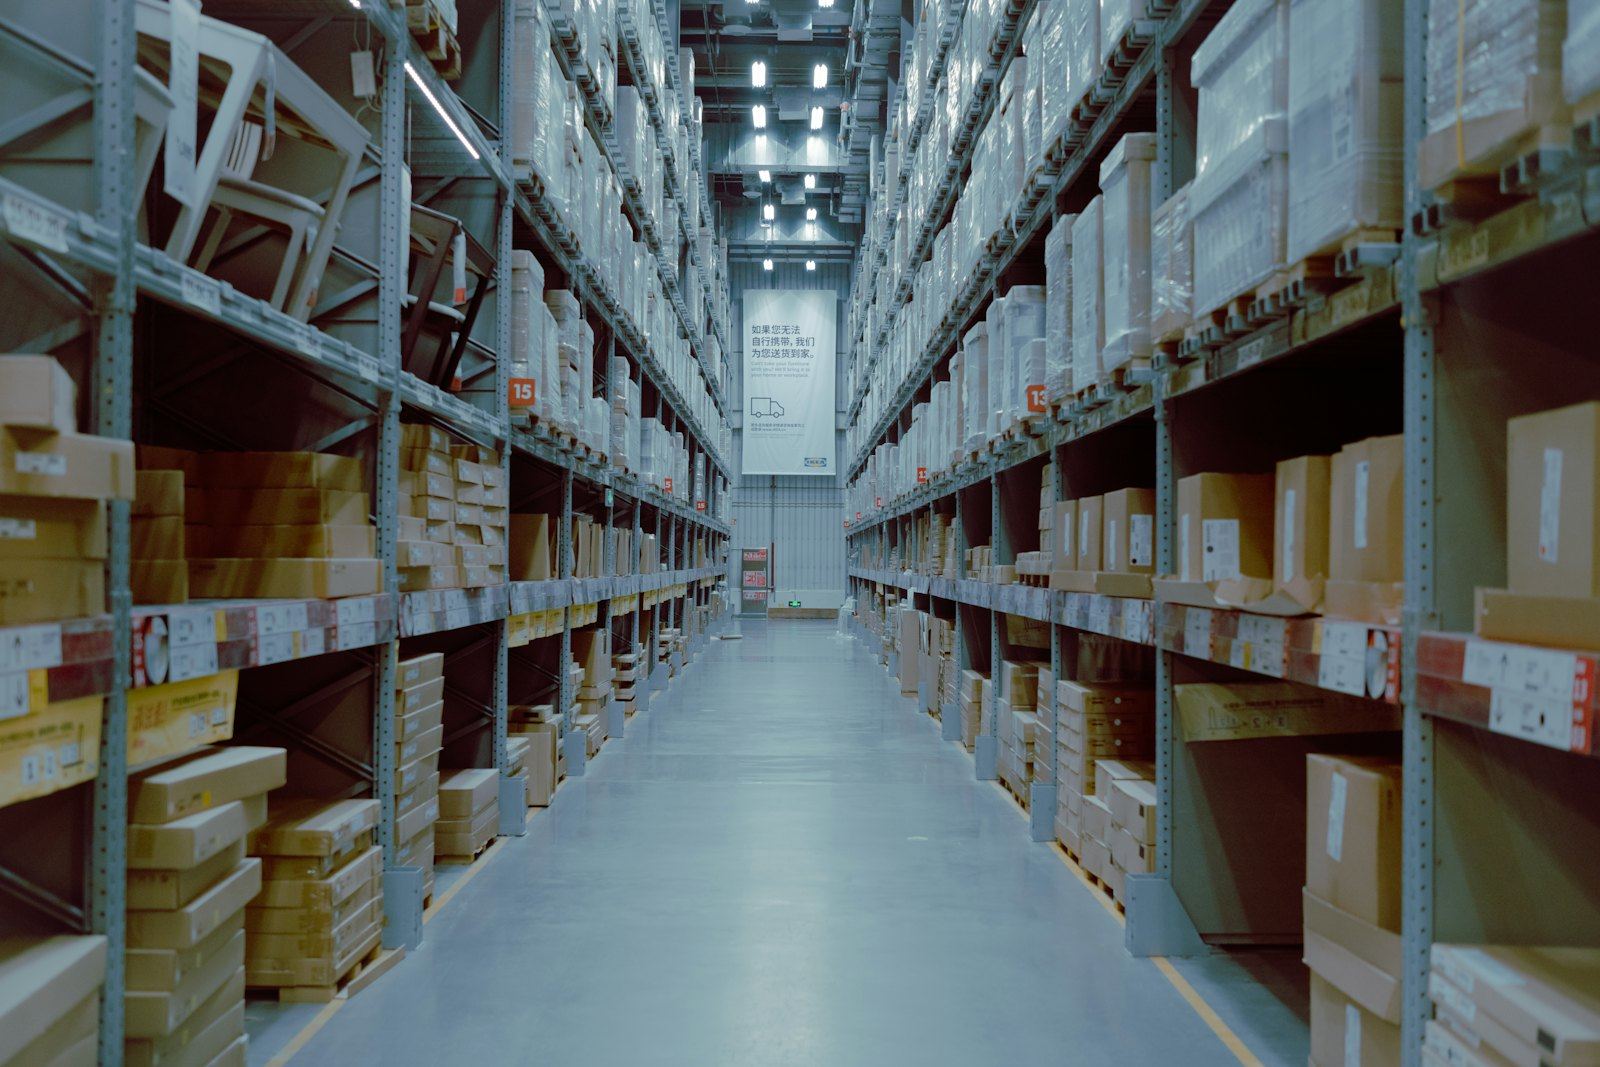
PwC's Working Capital Study 25/26 looked at more than 17,000 listed companies. In the UK, net working capital days have risen 48% since 2015, the steepest increase of any region in the study. Medium-sized companies did worst on stock. Their days inventory outstanding rose 24.2% over the decade, about 15 days, against 5.5% for large companies.
That gap tells you something. Large companies have planning teams, inventory analysts and lenders asking hard questions every quarter. Mid-sized firms built buffers during the pandemic and the shipping shocks that followed, and many never took them down. PwC puts roughly €300 billion of excess working capital in inventory across cash-intensive sectors in Western markets.
The money hasn't gone anywhere; it is sitting put on your own racking.
The usual hiding places
Stock reports sorted by value point attention at the big lines. The cash usually hides somewhere less obvious.
Safety stock set once and never revisited. Cover was raised to eight weeks in 2021 because a supplier kept missing dates. The supplier recovered. The parameter didn't.
Minimum order quantities nobody challenged. A buyer accepts a supplier's MOQ for a price break of a few per cent, then holds nine months of a slow line. The purchase price variance looks good. The cash cost never appears on it.
Duplicate buffers across sites. Two warehouses each hold their own safety stock for the same SKU, because systems don't share visibility or because each site manager is measured on availability and nobody is measured on the total.
The long tail. In most ranges a large share of SKUs moves a small share of volume. Each tail line looks too small to bother with. Added together they can carry a surprising part of the balance sheet.
Work in progress. Manufacturers look hard at raw materials and finished goods and much less at what sits between them, waiting for a component, a test or a decision.
Stock bought against a forecast that sales no longer believe. This one is political. The number stays in the system because changing it means admitting it was wrong.
Stock bought ahead. S&P Global's UK manufacturing PMI for June 2026 credited strategic stockpiling, ahead of price rises and amid Middle East supply problems, for part of the output lift, and said the effect was already fading. Stock bought to beat a price rise needs a plan to run it down once the risk has passed. Most businesses don't write one.
Putting a number on it
An illustrative example, not a client. A distributor with £28m annual cost of sales holds 95 days of stock, about £7.3m. Bringing that to 75 days, still well above the 62.8 days PwC reports for UK cash-intensive sectors in 2024, means holding about £5.75m. The difference, roughly £1.5m, is cash.
At current rates that cash isn't cheap. The Bank of England held Bank Rate at 3.75% in September 2026, and three of the nine committee members voted to raise it. Mid-sized borrowers pay a margin on top. If your all-in cost of funds is 7%, that £1.5m costs over £100,000 a year in interest alone, before storage, insurance, handling and the write-downs old stock eventually forces.
Those write-downs deserve attention from the FD. Under FRS 102, inventory has to be tested for impairment at each reporting date and written down where selling price less costs to complete and sell falls below carrying value, as ICAEW's factsheet sets out. A good share of excess stock is impairment that hasn't been recognised yet.
Where to start, and who owns it
Start with data you already have: twelve months of issues by SKU and site, current stock, open purchase orders and the planning parameters. Gathering it usually takes a couple of weeks, mostly because the parameters live in more places than anyone expects.
Then split the stock in two. The part that will sell, where the fix is to stop reordering and let it run down. And the part that won't, which needs a decision on return, resale, rework or recovery. The first part is usually larger and faster. Open purchase orders are the quickest lever of all, because deferring or cancelling an order protects cash that hasn't left the bank yet.
Ownership is where most efforts stall. Sales want availability, operations want stable runs, procurement wants price breaks and finance wants cash. Each position is rational, and nobody owns the total. Give one person a cash target in pounds, a weekly review and the authority to change parameters. Within ninety days you should see the run-down starting. Banking most of it takes six to twelve months, depending on how slow the slow lines really are.
One warning. Cutting stock without changing the reorder logic gives you a good quarter and a bad year. Shortages follow, sales lose faith in the plan, and the buffers creep back in by the back door. The release only holds if the parameters change with it.
More from BankStreet Partners.
Better payment terms without damaging supplier relationships
Stretching suppliers to 120 days is on its way out in UK law. The businesses that improve their cash position now will do it by trading, not by squeezing.
Read the article →
Do you need a procurement team, or procurement done?
A board that wants lower costs and fewer supply surprises is buying an outcome. Hiring a team is one way to get it, and not always the cheapest.
Read the article →
Slow and obsolete stock: return, resell, rework or recover?
Dead stock is a decision nobody wants to make. Making it early recovers more cash, and the rules on what you can do with it changed in 2026.
Read the article →Follow us on LinkedIn.
Occasional insights from BankStreet Partners. New articles, tools and what we are seeing across supply chains go on LinkedIn first.